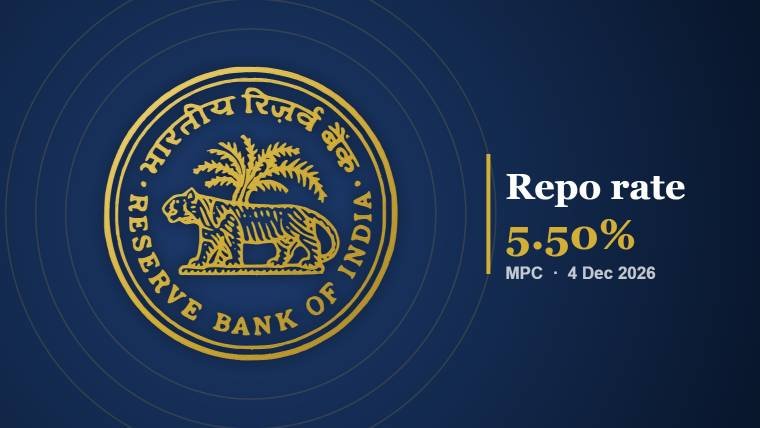
If you have a home loan, a car loan or are planning to take one, mark 4 December in your calendar. That is the day the Reserve Bank of India is widely expected to raise interest rates again, and your EMI could follow.
Here is what is going on, how much more you might pay, and what you can do about it, without the jargon.
Why is the RBI worried?
In one word: prices. Retail inflation hit 6.09% in October, up from 5.54% in September and the highest in two years. That is above 6%, the upper limit the RBI is legally supposed to keep inflation under.
Food is the main culprit. Food inflation jumped to 8.94%, and onion prices more than doubled from a year ago. Expensive crude oil and a weak rupee, which makes imports costlier, are adding to the pressure.
Didn’t the RBI just raise rates?
Yes. In October the RBI raised the repo rate by 0.25 percentage points to 5.50%, its first hike in nearly three years. It also changed its stance to “calibrated tightening”, which is central-bank speak for: no rate cuts for now, and more hikes are possible.
The repo rate is the rate at which banks borrow from the RBI. When it goes up, banks’ own borrowing costs rise, and they pass that on to you through higher loan rates.
So what will happen on 4 December?
The RBI’s Monetary Policy Committee meets from 2 to 4 December, and the decision is announced on the last day. After the October inflation numbers, most economists expect another 0.25 percentage point hike, taking the repo rate to 5.75%. SBI Research, which had earlier predicted a bigger 0.50 point “jumbo” hike, has scaled that back to 0.25 points, as oil prices have eased and the rupee has steadied.
Nothing is certain until the announcement. But a pause now looks less likely than a hike.
How much more could your EMI be?
Here is a simple example. We assume a home loan starting at 7.50% (SBI’s regular home loans now range from 7.50% to 8.80%) and a car loan at 9%, and show what happens if your bank passes on a 0.25 or 0.50 point increase.
| Loan | EMI today | If rate rises 0.25 pts | If rate rises 0.50 pts |
|---|---|---|---|
| ₹50 lakh home loan, 20 years (7.50%) | ₹40,280 | ₹41,047 (+₹768) | ₹41,822 (+₹1,542) |
| ₹30 lakh home loan, 20 years (7.50%) | ₹24,168 | ₹24,628 (+₹461) | ₹25,093 (+₹925) |
| ₹8 lakh car loan, 5 years (9%) | ₹16,607 | ₹16,704 (+₹97) | ₹16,801 (+₹195) |
Over 20 years, even a 0.25 point rise on a ₹50 lakh loan adds up to about ₹1.8 lakh in extra interest. That is why it is worth paying attention.
Many banks don’t raise your EMI at all. They quietly stretch your loan instead.
Will your EMI actually go up?
It depends on two things.
- What your loan is linked to. Most home loans taken since October 2019 are linked to an external benchmark, usually the repo rate itself. These change fast: under RBI rules, the rate must be reset at least once every three months. Older loans linked to a bank’s MCLR change more slowly. HDFC Bank, for example, raised its MCLR by up to 0.15 points from 7 November.
- Whether your bank raises the EMI or the tenure. Many banks keep your EMI the same and add months to your loan instead. On a new ₹50 lakh, 20-year loan, a 0.25 point rise would add roughly 11 extra months of payments. You don’t feel it today, but you pay more in total.
What you can do now
- Check your loan statement to see whether your loan is linked to the repo rate or MCLR, and when it next resets.
- Prepay a little if you can. Even a small part-payment early in the loan cuts total interest sharply. Most floating-rate home loans for individuals carry no prepayment penalty, but check with your bank.
- Ask about switching. If your rate is well above what new borrowers get, ask your bank for a lower rate or consider a balance transfer. Compare the fees first.
- Watch your tenure, not just your EMI. If your bank keeps extending the loan, ask to raise the EMI instead, so you don’t end up paying for years longer.
- Savers, there is good news. When rates rise, banks usually raise fixed deposit rates too. If you are planning an FD, it may be worth waiting until after 4 December to lock in a better rate.
The bottom line
With inflation above 6%, the RBI is likely to raise rates again on 4 December, most probably by 0.25 points. For a typical home-loan borrower, that means a few hundred rupees more a month, or a longer loan. It’s not a crisis, but it is a good moment to check your loan, think about prepaying, and shop around. We will update this article as soon as the RBI announces its decision.
This article is for information only and is not financial advice. Speak to your bank or a qualified adviser about your own loan.
Frequently asked questions
What is the repo rate today?
5.50%. The RBI raised it from 5.25% on 7 October 2026. Its next decision is due on 4 December 2026.
Will a repo rate hike increase my existing home loan EMI?
If your loan is linked to the repo rate, your rate will rise at the next reset, usually within three months. Your bank may raise your EMI or extend your loan tenure instead. Loans linked to MCLR change more slowly. Fixed-rate loans don’t change during the fixed period.
Why is inflation so high in India right now?
Mainly food prices. Food inflation reached 8.94% in October, with onion prices more than doubling. Expensive crude oil and a weaker rupee have also pushed up the cost of imported goods.
Is it a good time to open a fixed deposit?
Rising interest rates usually lead banks to raise FD rates. If you expect rates to rise further, a shorter FD now or waiting until after the RBI’s decision may help you lock in a better rate later.
Sources
- RBI: Resolution of the Monetary Policy Committee, 5–7 October 2026
- ThePrint: October retail inflation breaches RBI’s 6% ceiling (12 November 2026)
- Free Press Journal: Retail inflation hits 24-month high, food inflation 8.94%
- OneIndia: SBI Research expects a 25 bps hike in December
- Business Today: SBI raises home loan rates by 25 bps (18 October 2026)
- Free Press Journal: HDFC Bank raises MCLR by up to 15 bps (10 November 2026)
Read next
Discover more from Khabar Mitra
Subscribe to get the latest posts sent to your email.